When business owners hear the word “pollution,” they often picture smokestacks, chemical plants, or hazardous waste sites.
For many small and midsized businesses, that leads to a dangerous assumption:
“We don’t create pollution, so it doesn’t apply to us.”
Unfortunately, insurance companies, regulators, and the courts often see things differently.
Pollution claims can arise from surprisingly ordinary business activities, and many commercial property and liability policies either exclude them entirely or provide only very limited coverage.
Understanding where these exposures come from is the first step toward managing them.
What Is Pollution Liability?
In simple terms, pollution liability is the financial responsibility for bodily injury, property damage, environmental cleanup, or legal costs resulting from the release of contaminants into the environment.
A release doesn’t have to involve a major disaster. It can result from a slow leak, an accidental spill, improper disposal of waste, or even indoor air quality problems.
Cleanup costs alone can be substantial, even before considering lawsuits or business interruption.
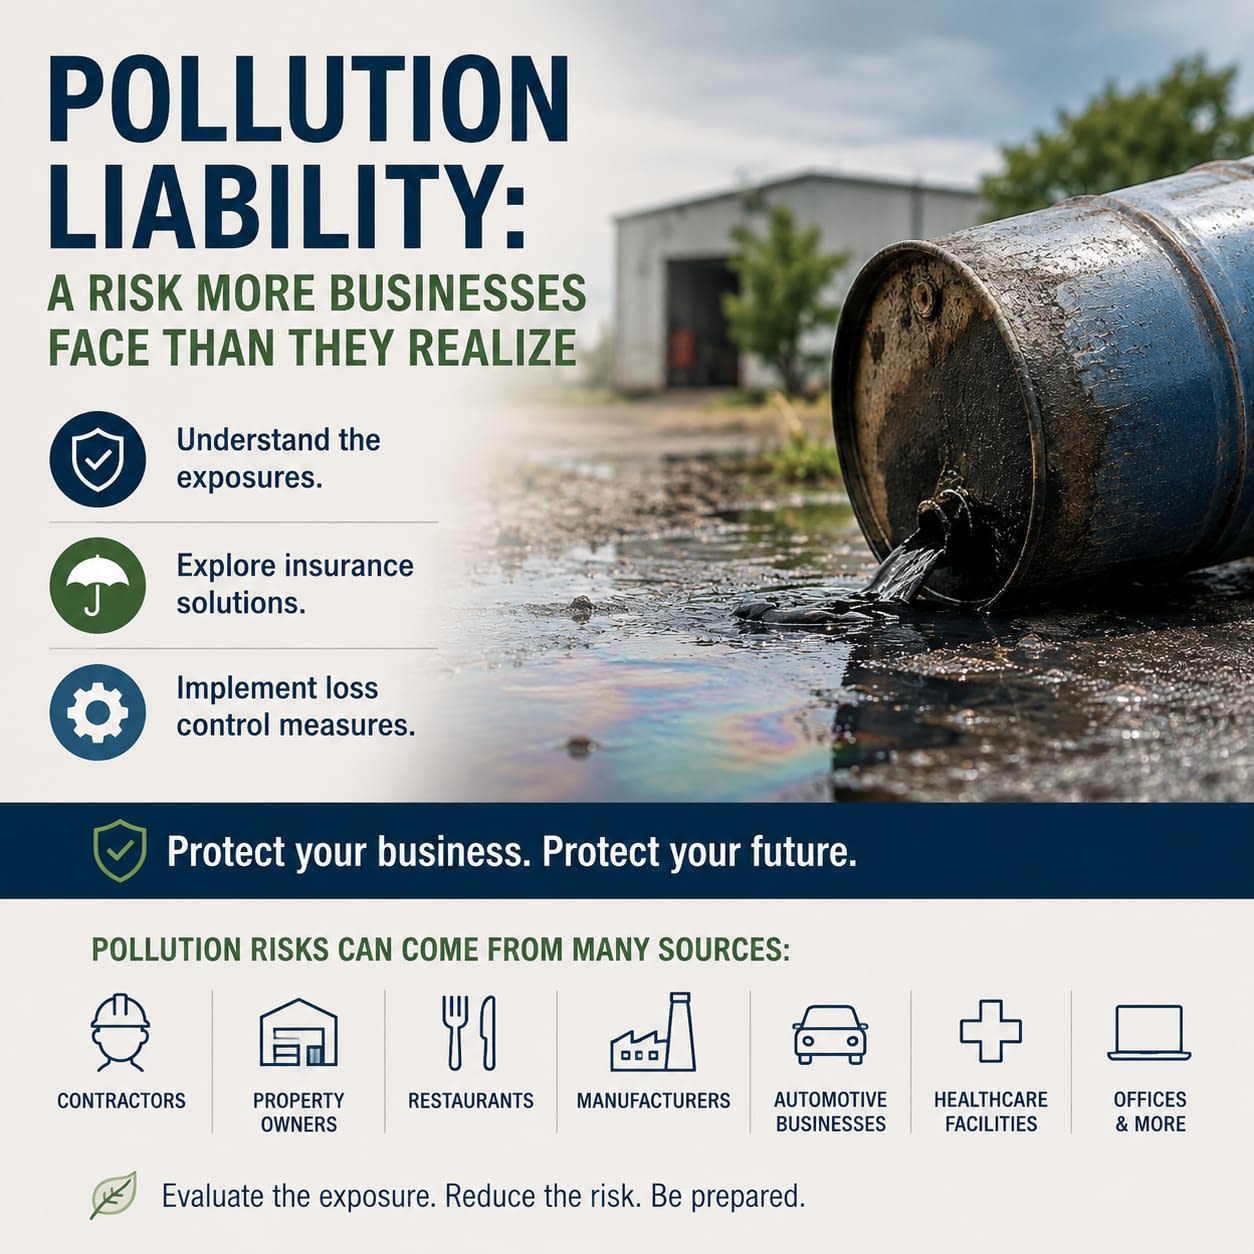
Pollution Exposures Exist in More Businesses Than You Think
Many business owners don’t realize they have pollution exposures because they don’t manufacture chemicals or handle hazardous waste.
Here are just a few examples.
Contractors
Contractors frequently use products that can become pollutants if released improperly.
Examples include:
- Paints and coatings
- Solvents
- Adhesives
- Fuel for equipment
- Hydraulic fluids
- Asphalt products
- Concrete washout water
A ruptured fuel tank, improper disposal of materials, or contaminated runoff from a job site can all create liability.
Property Owners and Landlords
Owning property creates its own environmental responsibilities.
Potential exposures include:
- Heating oil tanks
- Fuel storage
- Sewer backups
- Mold resulting from water damage
- Asbestos disturbed during renovations
- Lead paint
- Refrigerant leaks
- Contaminated soil from previous owners
In many cases, ownership alone can create responsibility, even if the current owner did not cause the contamination.
Restaurants and Food Businesses
Restaurants may generate pollutants through:
- Grease disposal
- Cleaning chemicals
- Refrigeration systems
- Fuel storage
- Wastewater discharge
Improper handling or disposal can result in regulatory action as well as third-party claims.
Manufacturers
Manufacturing operations often involve:
- Chemicals
- Oils
- Lubricants
- Metal finishing compounds
- Dust
- Wastewater
- Air emissions
Even relatively small manufacturers can face significant cleanup obligations after an accidental release.
Automotive Businesses
Repair shops, dealers, body shops, and fleet operations may handle:
- Motor oil
- Antifreeze
- Batteries
- Solvents
- Paint
- Fuel
- Brake fluid
A leaking underground storage tank or improper waste disposal can become an expensive environmental claim.
Healthcare Facilities
Medical practices and laboratories may have exposures involving:
- Medical waste
- Pharmaceuticals
- Cleaning chemicals
- X-ray processing materials
- Sharps disposal
These exposures often extend beyond patient care.
Offices
Even businesses that appear to have little environmental exposure aren’t automatically immune.
Potential issues include:
- Mold following a plumbing leak
- Fuel spills from emergency generators
- Refrigerant leaks from HVAC systems
- Indoor air quality claims
- Improper disposal of electronic waste
Why General Liability Insurance May Not Be Enough
Many business owners assume their Commercial General Liability (CGL) policy covers pollution claims.
In reality, the standard CGL policy contains a broad pollution exclusion that eliminates coverage for many pollution-related losses.
While there are exceptions, they are limited and should not be relied upon as comprehensive protection.
That means a business could face:
- Environmental cleanup costs
- Legal defense expenses
- Property damage claims
- Bodily injury claims
- Regulatory fines and penalties where insurable by law
- Business interruption resulting from a pollution event
Without specialized coverage, these costs may have to be paid out of pocket.
Pollution Liability Insurance
Pollution Liability Insurance is designed to fill many of the gaps left by standard liability policies.
Depending on the policy, coverage may include:
- Third-party bodily injury
- Property damage
- Environmental cleanup costs
- Legal defense
- Transportation-related pollution
- Disposal site liability
- Emergency response expenses
- Some first-party cleanup costs
Coverage varies significantly between insurance companies, so it’s important to understand exactly what is and is not covered.
Some policies are written specifically for contractors, while others are designed for property owners, manufacturers, transportation companies, or businesses with unique environmental exposures.
Insurance Is Only Part of the Solution
The best pollution claim is the one that never happens.
Good loss control practices can significantly reduce both the likelihood and severity of a pollution incident.
Examples include:
- Proper storage of fuels and chemicals
- Secondary containment for liquid storage
- Routine inspection of tanks, piping, and equipment
- Employee training on spill prevention and response
- Written spill response procedures
- Proper waste handling and disposal
- Careful contractor oversight
- Regular HVAC maintenance
- Prompt repair of water leaks to reduce mold growth
- Compliance with environmental regulations
Many insurers look favorably on businesses with documented environmental management practices, which may improve underwriting results.
Questions Every Business Owner Should Ask
If you answer “yes” to any of these questions, it may be worth discussing pollution liability with your insurance advisor.
- Do we store fuel, chemicals, oils, or cleaning products?
- Could a spill leave our property?
- Do we own or lease commercial property?
- Do we perform work at customer locations?
- Could water damage lead to mold?
- Do we dispose of hazardous or regulated waste?
- Could an environmental incident interrupt our business?
- Would we be able to pay for a major cleanup without insurance?
Final Thoughts
Pollution liability isn’t just an issue for chemical manufacturers or large industrial operations. It can affect contractors, property owners, retailers, healthcare providers, restaurants, manufacturers, service businesses, and many others.
The challenge is that many businesses don’t recognize the exposure until after a loss occurs, and by then it’s too late to add coverage.
Every business is different. The right combination of insurance and loss control depends on your operations, the materials you use, where you work, and the property you own or occupy.
A periodic review of your operations can help identify environmental exposures before they become expensive surprises.